Restaurants, Cafes & Bars
Restaurant Insurance
Insurance for the kitchens, dining rooms, and bars that feed and serve Alberta.
Get your restaurant insurance quote
How do you prefer to work through your insurance?
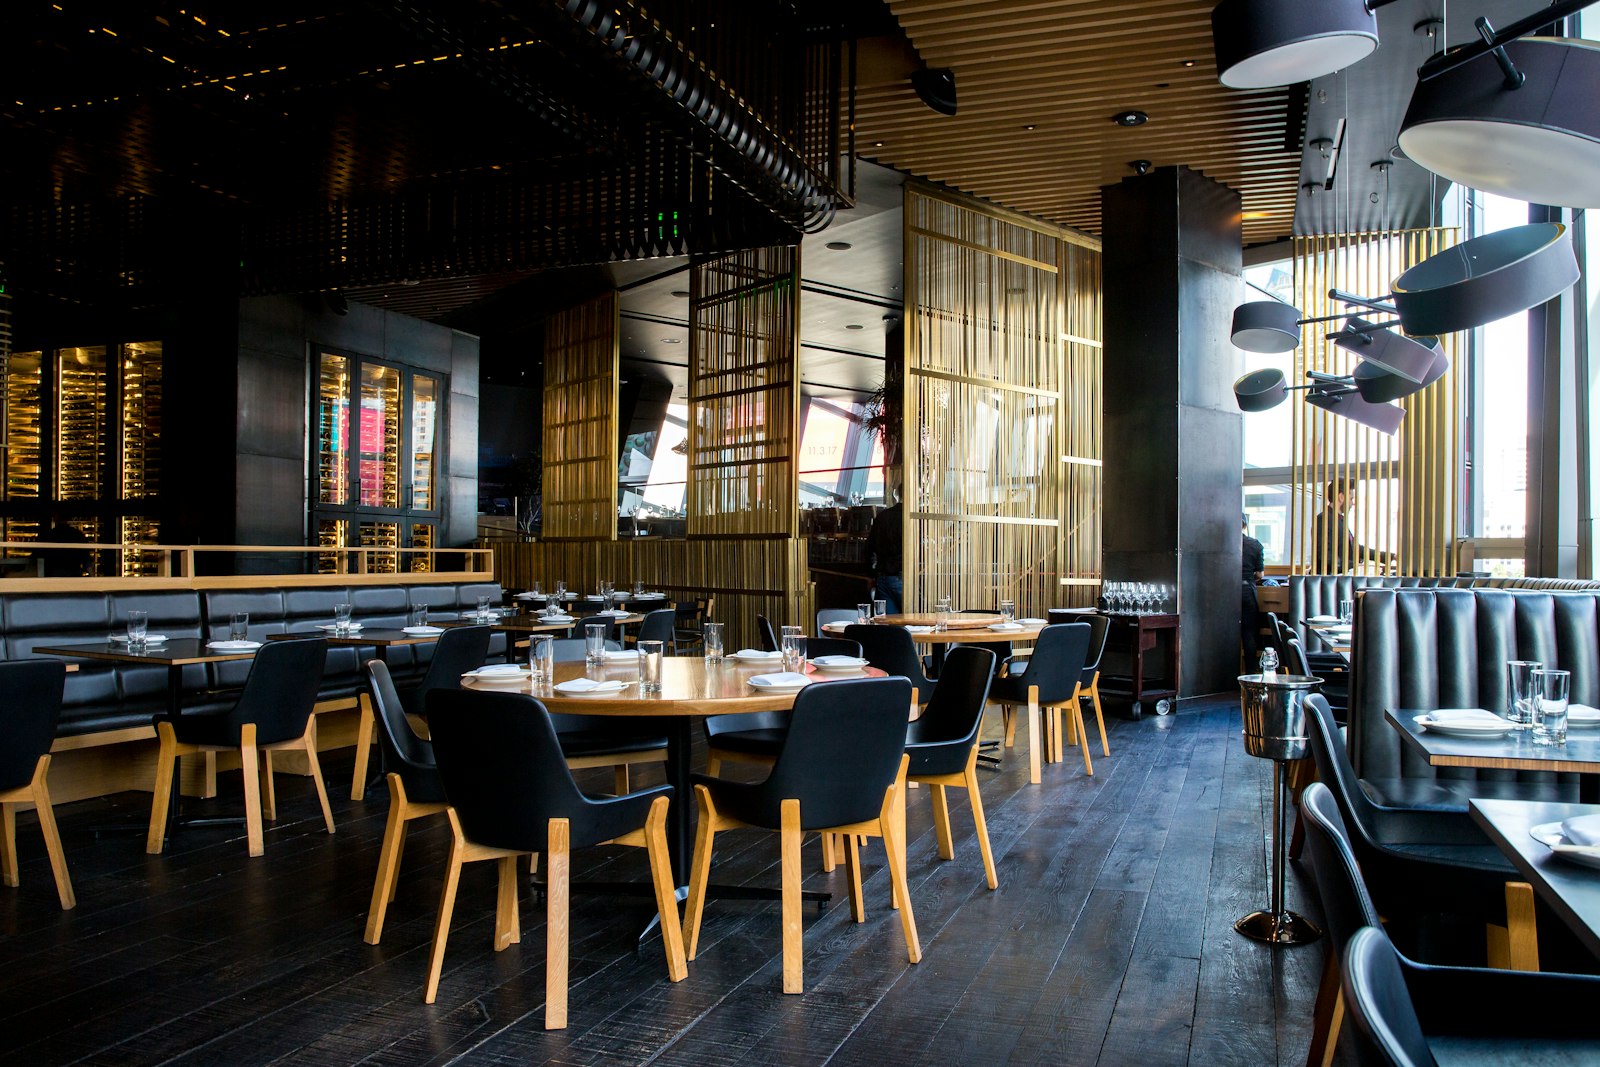
Restaurant insurance is a package built for food and drink businesses. It brings together general liability for a customer who is hurt or made ill, liquor liability if you are licensed to serve, property coverage for your build-out and kitchen, business interruption when the doors close, equipment breakdown and spoilage when the refrigeration fails, and cyber protection for the payment data you hold. A busy kitchen, an open dining room, hot equipment and often a liquor licence put a lot of exposure under one roof. Cafe, family restaurant, fine dining, pub or bar, Velocity builds these programs for restaurants across Alberta, sized to how your business runs.
The Exposure
Risks you face.
A restaurant concentrates the public, open flame, refrigeration, and, often, alcohol in one space. Each is a different kind of exposure.
A customer injured on your premises
Wet floors, crowded dining rooms, patios and stairs are constant sources of slip-and-fall claims. Even a minor injury can mean thousands in legal defence before any settlement, and general liability is the policy that pays it.
Food-borne illness and a product you served
A customer who becomes ill, or has an allergic reaction to an ingredient, can name the restaurant. That product and food liability exposure is generally covered within your general liability policy. It is one reason that coverage is the foundation of every restaurant program.
Serving alcohol, and liquor liability
If you are licensed to serve alcohol, your business can be held responsible for injury or damage caused by a patron who was over-served. Liquor liability responds to that exposure, and Alberta expects your servers to be ProServe-trained.
Fire, water, and damage to your build-out
Commercial kitchens are a leading source of fire, and a burst pipe or a fire next door can close you for weeks with your build-out, kitchen equipment and contents all exposed.
Equipment failure and spoiled stock
A walk-in cooler or freezer that suffers a sudden and unexpected breakdown can spoil a room full of stock overnight and stop service. That internal failure is left out of a standard property policy and needs equipment breakdown coverage.
Lost income after a shutdown, and cyber
When a covered loss closes the doors, the rent, payroll and supplier bills keep coming. Your point-of-sale, online ordering and reservation systems also hold payment and customer data. Alberta’s PIPA governs that data, so a breach carries a duty to notify.
The Protection
Coverages we recommend.
Commercial General Liability
Injury or property damage to a customer or a member of the public, including a slip on your floor and illness or a reaction tied to the food you served. $2 million is now the standard minimum limit, and this is the one policy no restaurant should be without.
Liquor Liability
For licensed premises, this responds when your business is held responsible for injury or damage caused by a patron who was over-served. Any restaurant, pub or bar holding an AGLC licence needs it.
Commercial Property
Your build-out, kitchen equipment, furniture and stock, protected against fire, water, theft and vandalism. Insure to the right value so co-insurance does not cut a claim down.
Business Interruption
This replaces lost income and covers rent, payroll and ongoing expenses if a covered loss closes the restaurant, which matters most to a single-location operation running on thin margins.
Equipment Breakdown
The sudden and unexpected failure of refrigeration, cooking equipment and building systems, plus the spoiled stock and lost income that follow, all of which a standard property policy leaves out.
Crime & Cyber
Crime coverage responds to employee theft, robbery and fraud. Cyber covers a breach of the payment and customer data in your point-of-sale and booking systems. That includes the notification Alberta’s PIPA requires.
Coverages shown are general examples, not a description of any specific policy. Policy coverages widely vary and should be confirmed with your broker.
How your coverage fits Alberta’s rules
Running a restaurant in Alberta means meeting rules that insurance does not replace. Your kitchen needs a food-establishment permit and is inspected by Alberta Health Services under the Public Health Act and the Food Regulation, and most cities also require a municipal business licence. If you serve alcohol, you need a licence from Alberta Gaming, Liquor and Cannabis, and your servers are expected to hold ProServe certification, both of which sit behind your liquor liability coverage. And because your point-of-sale and reservation systems hold customer and payment data, Alberta’s Personal Information Protection Act sets out what you must do, including notifying the Privacy Commissioner, if that information is breached. We build your program to sit alongside every one of those rules.
Why restaurants choose Velocity
We work with cafes, family restaurants, fine dining rooms, pubs, and bars, and we know where the risk sits. The liquor licence, the kitchen fire and refrigeration exposure, the thin margins that make business interruption matter, and the data your systems hold. We size the program to how you operate, whether you serve alcohol or not, and we issue the certificates a landlord or supplier asks for without delay.
How Pricing Works
What drives your premium
- Whether you serve alcoholA licensed restaurant, pub or bar carries liquor liability exposure that a dry cafe does not, and the share of your sales that comes from alcohol is one of the biggest drivers of price.
- Type of food and cookingDeep frying, open flame and high-volume kitchens carry more fire risk than a cafe or a cold-prep menu, so what and how you cook affects the premium.
- Annual revenue & seatingHigher sales, more seats and patios mean more customers and more exposure. Your volume is a core input the insurer prices against.
- Your build-out & kitchen equipmentThe value of your leasehold improvements, kitchen equipment and contents sets the property side of the premium, and it needs to reflect what you have invested.
- Location & hoursThe building, the neighbourhood, late-night hours and local hazards like hail all factor into both liability and property pricing across Alberta.
- Fire protection & safetyA maintained hood-and-duct suppression system, regular cleaning, alarm monitoring and ProServe-trained staff all cut risk and can bring the premium down.
- Claims history, limits & deductiblesA clean record lowers your price while past injury, liquor, fire or theft claims raise it. More coverage costs more, and choosing a bigger deductible buys the premium down while raising what you pay per claim.
Common Questions
Questions ownersreally ask.
Do I need liquor liability if my restaurant serves alcohol?
Yes. If you hold an AGLC licence, your business can be held responsible for injury or damage caused by a patron who was over-served, and liquor liability is the coverage that responds. Alberta also expects every member of your serving staff to be ProServe-trained. We make sure the coverage matches your licence and how you serve.
Is a customer getting sick from my food covered?
That is a food and product liability claim, and it is generally covered within your commercial general liability policy. It responds when a customer becomes ill or has a reaction tied to the food you served. Good food-safety practices and Alberta Health Services compliance cut the risk, but the coverage is there for when a claim still comes.
What happens if my walk-in cooler breaks down and I lose all my stock?
If the cooler suffers a sudden and unexpected breakdown, equipment breakdown coverage can pay for the spoiled stock and the income you lose while it is down. That internal failure is specifically left out of a standard property policy, and this is the gap it fills. It does not cover a unit that simply wears out, so maintenance still matters.
How much general liability coverage should a restaurant carry?
$2 million is now widely regarded as the standard minimum for any one claim, and many landlords and suppliers ask for at least that. Busier rooms, patios and licensed premises may warrant more. We match the limit to your operation and the agreements you work under.
Do I need a business licence and permits to open a restaurant in Alberta?
Yes. You need a food-establishment permit and are inspected by Alberta Health Services, most cities require a municipal business licence, and serving alcohol requires an AGLC licence. These are separate from insurance, but they shape the coverage you need, and we build the program to line up with them.
Does insurance cover a kitchen fire?
Fire is a covered cause under most commercial property policies, and commercial kitchens are a leading source of it. What matters is that your build-out, equipment and contents are insured to the right value, that you carry business interruption for the closure that follows, and that your suppression system and cleaning are maintained. We go through all of it with you before the policy is set.
Built for the kitchen,the dining room, and the bar.
Tell us what you serve and whether you hold a liquor licence, and we’ll size coverage to your kitchen, your dining room, and the way you operate. Most restaurants are bound within a few business days of that first call.
Not ready to switch? Book a 15-minute coverage review instead
Related
Keep exploring
17 pages
Related