Guides
The broker of record letter, explained
Moving brokers and moving insurers are two different actions. Here is how a broker of record letter works.
Greater Edmonton
One experienced broker handles your file from the first quote through to the claim call, and you speak to that same person every time. This page is about why Edmonton owners move to us and then stay.
Most Edmonton businesses do not change brokers over price. They change because nobody called them back. This is a market dominated by large, volume-driven offices where a commercial file is a row in somebody’s queue, and the person who sold you the policy is rarely the person you reach afterwards. Velocity was built as the alternative to that, one relationship at a time. Mandy Stierman spent over twenty years inside brokerages, across front-line underwriting, complex placements, hard-market renewals and claims advocacy, and she founded this one after watching good businesses get handed to whoever happened to be free that morning.
Why Owners Move
The file gets sold by one person, serviced by another and renewed by a third, and none of them carries the history. You end up explaining your own business back to your broker every year. That is the complaint we hear most often in a first call with an Edmonton owner.
A machine shop in the industrial northeast, a clinic off Whyte and a landlord with four walk-up buildings are three different risks, and they are routinely sold the same package with the name changed. The gaps surface at claim time, when the wording turns out to describe somebody else’s business.
A renewal that gets rubber-stamped drifts upward. Nobody re-tests the market, nobody asks whether the revenue figure is still right, and nobody mentions that the limit you bought four years ago would no longer rebuild the building.
Certificates take four days because the request sits in a queue. Nobody can say offhand what your limits are, what changed at the last renewal or what is still outstanding. The information exists somewhere in a file you have no access to, and getting a straight answer means waiting for somebody to go and look it up.
Why We Stand Out
Your Broker
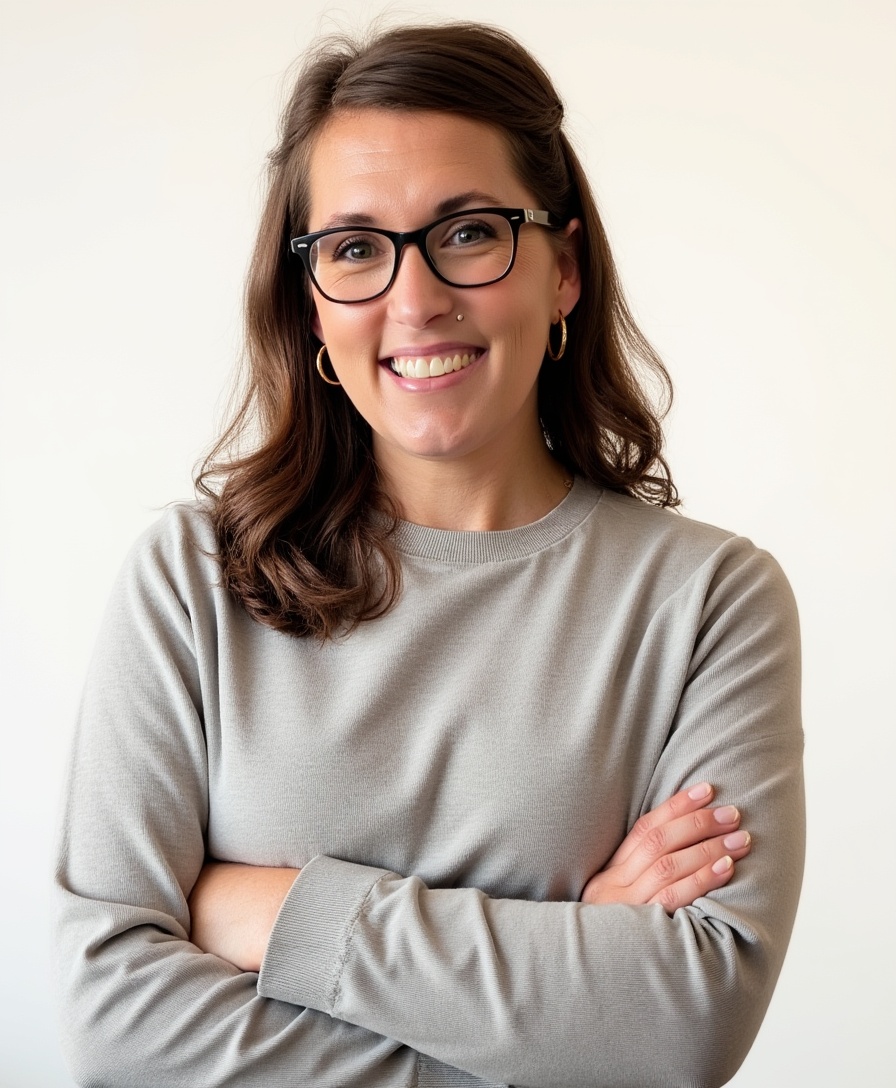
Mandy Stierman · Founder & Principal Broker
Licensed Alberta broker · 20 years in insurance
Velocity Insurance Inc. is a proudly independent, female-led commercial brokerage founded and owned in Alberta. Mandy was formerly an Account Executive with Spruceland Insurance and is a member of the Insurance Brokers Association of Alberta.
“She took the time to explain everything clearly in a way that actually made sense… her rates were more than competitive, and the level of service she provided was truly exceptional. It’s so refreshing to work with a woman entrepreneur who is not only amazing at what she does, but also genuinely cares about her clients.”
TJ Aneca · a month ago · Google
Reviews come from clients across Alberta, Edmonton included. Read them on Google
Common Questions
Edmonton is where the brokerage was founded and where most of its clients are. We run remotely by design, so your file is handled by phone and email instead of by appointment, and we meet in person when you would rather do that. Being an Alberta brokerage means the same licence and the same markets wherever you are in the province.
Mandy Stierman, the owner and principal broker. She quotes the file, places it and services it, and she is who you reach when you call. There is no handover to a service team once the sale is done.
Scale works against you on a commercial file. A large office measures itself in policies processed, so your account gets standardised and your questions get queued. We took the opposite trade deliberately. Fewer clients, one experienced broker on each of them, and enough market access to move a file that has stopped being competitive.
Because we have to demonstrate it every year. With fourteen insurance partners behind us there is no house insurer taking the file by default, and you see what the alternatives quoted. A broker tied to one company can only tell you their number is the best one available to them.
We look at the file before it renews, check whether your revenue, payroll and operations have moved, and decide whether the market needs testing. If we remarket it you see what came back and the reasoning behind the recommendation. A renewal invoice with no conversation attached is not something we send.
Same business day for a question, and a certificate as soon as we can turn it around once your policy is bound. If something is going to take longer because the file is sitting with an underwriter, we tell you that up front instead of leaving you wondering.
Nothing you pay directly. The insurer pays a commission out of the premium it charges, and that sits in the price whether or not a broker is involved. Going direct does not remove the cost. It removes the person negotiating for you.
Easier than most owners expect, and it takes one signature. A broker of record letter moves your existing policy to us with the same insurer, the same wording and the same premium. Nothing is cancelled, nothing is re-underwritten, and there is no gap in cover at any point. You do not have to wait for your renewal date either. From the day it moves across, we have until that renewal to make the case that we were worth moving to.
Yes, and there is no charge or obligation for it. Send us your current policy documents and Mandy goes through them personally, then tells you where the gaps are, where the limits look wrong and whether the price is still competitive. If your coverage is already right you will be told that too, which happens more often than you might expect.
The Next Step
Send us what you have and we will tell you what we would do with it. If we are not the right brokerage for your business we will say so on the first call.
How do you prefer to work through your insurance?
Related
More about insurance in Edmonton
Industries we cover in Edmonton
Further reading
Guides
Moving brokers and moving insurers are two different actions. Here is how a broker of record letter works.
Guides
A broker is not a price comparison service with a person attached. Here is the job as it is really done, who pays for it, what the law requires of it, and how to tell whether you are getting it.
Guides
Three things move a commercial premium, and only one of them is about you. Here is how to work out which one moved yours, and which part you can do something about.