Guides
The broker of record letter, explained
Moving brokers and moving insurers are two different actions. Here is how a broker of record letter works.
Greater Edmonton
Clinics, professional offices and condominium boards need a broker who has placed those risks before. This page covers how we handle St. Albert accounts.
The commercial base here is older and more professional than most of the Edmonton region, and the exposures are less dramatic and considerably more detailed. A medical clinic carries diagnostic equipment and patient records governed by the Health Information Act. A condominium corporation carries a statutory obligation and a replacement cost figure that goes stale without anybody noticing. Neither is served by a package policy chosen from a dropdown. Velocity places these with markets that write them, which is a matter of having done it before rather than shopping harder.
Why Owners Move
A clinic sold a retail package has equipment breakdown missing and no cyber cover reflecting the records it holds. The premium looks fine right up until the moment the coverage is asked to do something.
Professional practices carry detail that takes time to learn, and a rotating account handler never gets there. You end up re-explaining your own regulatory obligations to whoever picked up.
For a condominium corporation that is a genuine risk, because the replacement cost valuation ages out of date while the premium goes up. Boards discover the shortfall after a water loss, which is the worst moment to find out.
Boards and practice owners have to explain the program to somebody else, whether that is owners at an annual meeting or a partner. That is difficult when nobody has explained it to you first.
Why We Stand Out
Your Broker
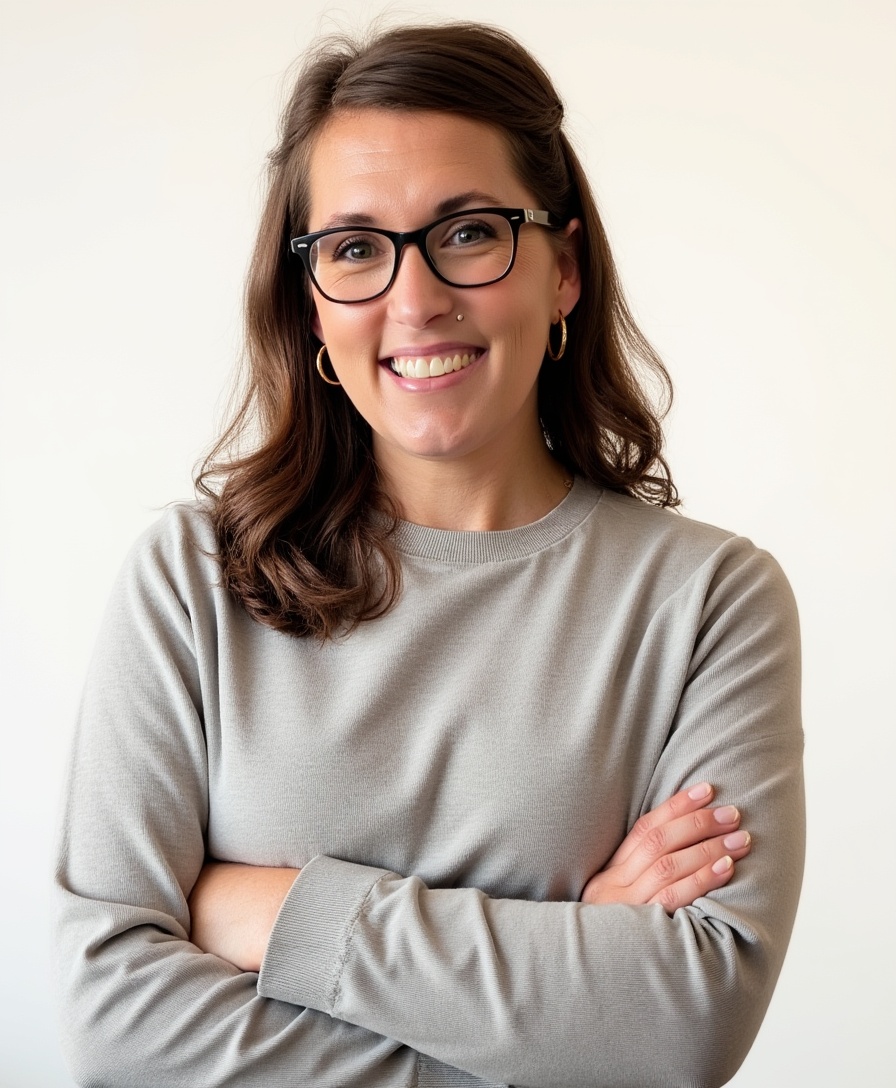
Mandy Stierman · Founder & Principal Broker
Licensed Alberta broker · 20 years in insurance
Velocity Insurance Inc. is a proudly independent, female-led commercial brokerage founded and owned in Alberta. Mandy was formerly an Account Executive with Spruceland Insurance and is a member of the Insurance Brokers Association of Alberta.
“She took the time to explain everything clearly in a way that actually made sense… her rates were more than competitive, and the level of service she provided was truly exceptional. It’s so refreshing to work with a woman entrepreneur who is not only amazing at what she does, but also genuinely cares about her clients.”
TJ Aneca · a month ago · Google
Reviews come from clients across Alberta, St. Albert included. Read them on Google
Common Questions
Yes, regularly. It is one of the closest parts of the book to us and covers retail, professional offices, clinics, trades and condominium corporations. We work remotely, and meet in person when a board would rather do that.
Mandy Stierman handles it herself from start to finish. She places the file, services it and will present to a board where that helps. Nothing is handed to somebody less familiar with it after the sale.
Detailed risks suffer most from volume servicing. A clinic or a condominium file rewards a broker who remembers last year, and a small book is the only reliable way to get that.
No insurer has a standing claim on the file, so it is tested against fourteen insurance partners and you see the outcome. That matters on specialist classes, where the spread between markets is much wider than on ordinary risks.
We look at it early and check the things that age badly, particularly building valuations and equipment schedules. If the market needs testing we test it and show you the alternatives with the reasoning.
Same business day for a question, and certificates as fast as we can once cover is bound. Board deadlines and annual meetings are worth telling us about in advance and we will work to them.
Nothing on top of the premium. The insurer pays a commission from what it already charges, so the cost is present either way. What you get is somebody who reads the wording before you have to rely on it.
A broker of record letter transfers the policy exactly as it is, with the same insurer, wording and premium, no cancellation and no gap. For a board that means no resolution to re-do and no coverage risk.
Yes, free of charge and with no obligation. Send the policy and any recent valuation, and Mandy will tell you whether the coverage matches the obligation and whether the numbers are still current.
The Next Step
Send us what you have and we will tell you what we would do with it. If we are not the right brokerage for your business we will say so on the first call.
How do you prefer to work through your insurance?
Related
More about insurance in St. Albert
Industries we cover in St. Albert
Further reading
Guides
Moving brokers and moving insurers are two different actions. Here is how a broker of record letter works.
Guides
A broker is not a price comparison service with a person attached. Here is the job as it is really done, who pays for it, what the law requires of it, and how to tell whether you are getting it.
Guides
Three things move a commercial premium, and only one of them is about you. Here is how to work out which one moved yours, and which part you can do something about.