Guides
The broker of record letter, explained
Moving brokers and moving insurers are two different actions. Here is how a broker of record letter works.
Calgary Region
Hospitality and retail carry exposures a general package handles badly, and Cochrane has a lot of both. This page covers how we build those programs.
The town has grown quickly without losing a real downtown, so the commercial base leans towards restaurants, pubs, shops and the trades serving a fast-expanding community, with a strong commuter tie to Calgary underneath it. Hospitality is the part that gets sold badly more often than anything else. Liquor liability, food spoilage and a tenant improvements limit that would genuinely rebuild the fit-out are three specific things that a general package tends to get wrong, and none of them surfaces until a claim. We place those risks with the markets that write them properly.
Why Owners Move
A pub sold a retail package is missing liquor liability and carrying a spoilage limit that would not empty one cooler. The premium looks reasonable right up until the night it needs to work.
Tenant improvement limits are the classic example. A fit-out gets valued once when the lease is signed and never revisited, so a rebuild years later runs well past what the policy will pay.
Hospitality operators work unsociable hours and need a broker who picks up, not a queue that opens at nine. Continuity is the difference between a quick reply and a week of messages.
Property pricing across the Calgary corridor has moved hard and a renewal nobody argued about absorbs the whole increase in silence. Nothing gets tested, and nobody explains which part of the rise was avoidable.
Why We Stand Out
Your Broker
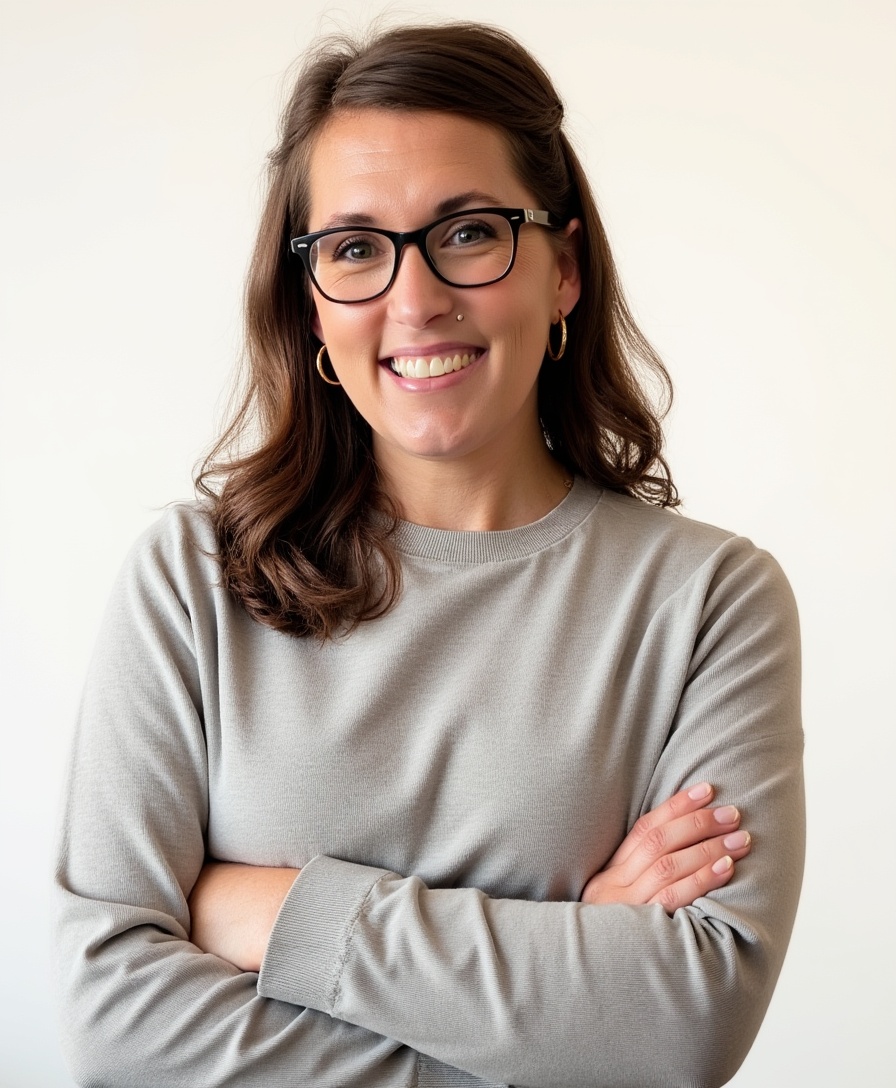
Mandy Stierman · Founder & Principal Broker
Licensed Alberta broker · 20 years in insurance
Velocity Insurance Inc. is a proudly independent, female-led commercial brokerage founded and owned in Alberta. Mandy was formerly an Account Executive with Spruceland Insurance and is a member of the Insurance Brokers Association of Alberta.
“She took the time to explain everything clearly in a way that actually made sense… her rates were more than competitive, and the level of service she provided was truly exceptional. It’s so refreshing to work with a woman entrepreneur who is not only amazing at what she does, but also genuinely cares about her clients.”
TJ Aneca · a month ago · Google
Reviews come from clients across Alberta, Cochrane included. Read them on Google
Common Questions
No. We are an Alberta brokerage working remotely across the province, and Alberta licensing is provincial, so the markets, wordings and claims handling are identical wherever the desk happens to be.
Mandy Stierman, the owner, who quotes the file, places it and services it herself. Hospitality operators tend to need a broker at awkward hours, and there is nobody in between.
Yes, and they are a normal part of the book. The three things we check first are liquor liability, spoilage cover and whether the tenant improvements limit would genuinely rebuild your fit-out at today’s cost.
Hospitality gets standardised at volume offices because it is fiddly and the accounts are small. We hold fewer files and place them with markets that write the class, which is most of the difference.
Insurer appetite for restaurants moves constantly, and with fourteen insurance partners we can move with it. You see what the alternatives came back at. A broker with one company can only offer whatever that company thinks of pubs this year.
It gets opened before the date, with particular attention to the tenant improvement figure and your income protection. If the market is worth testing we test it and show you what came back.
Same business day for questions and certificates as soon as we can turn them around once cover is bound. Where an underwriter is holding something up, we say so instead of going quiet.
Nothing beyond the premium. Commission comes out of what the insurer charges regardless, so buying direct keeps the cost and removes the person negotiating for you.
One broker of record letter transfers everything untouched, with the same insurer, wording and premium, no cancellation and no gap in cover. It can be done at any point in the year.
Yes, at no cost and with no obligation. Send the policy and Mandy will read it herself, paying particular attention to the limits that catch hospitality operators out.
The Next Step
Send us what you have and we will tell you what we would do with it. If we are not the right brokerage for your business we will say so on the first call.
How do you prefer to work through your insurance?
Related
More about insurance in Cochrane
Industries we cover in Cochrane
Further reading
Guides
Moving brokers and moving insurers are two different actions. Here is how a broker of record letter works.
Guides
A broker is not a price comparison service with a person attached. Here is the job as it is really done, who pays for it, what the law requires of it, and how to tell whether you are getting it.
Guides
Three things move a commercial premium, and only one of them is about you. Here is how to work out which one moved yours, and which part you can do something about.